Treasury Volatility Regimes
Elevated Rate Volatility Reshapes Sovereign Debt Risk Architecture
16 November 2026
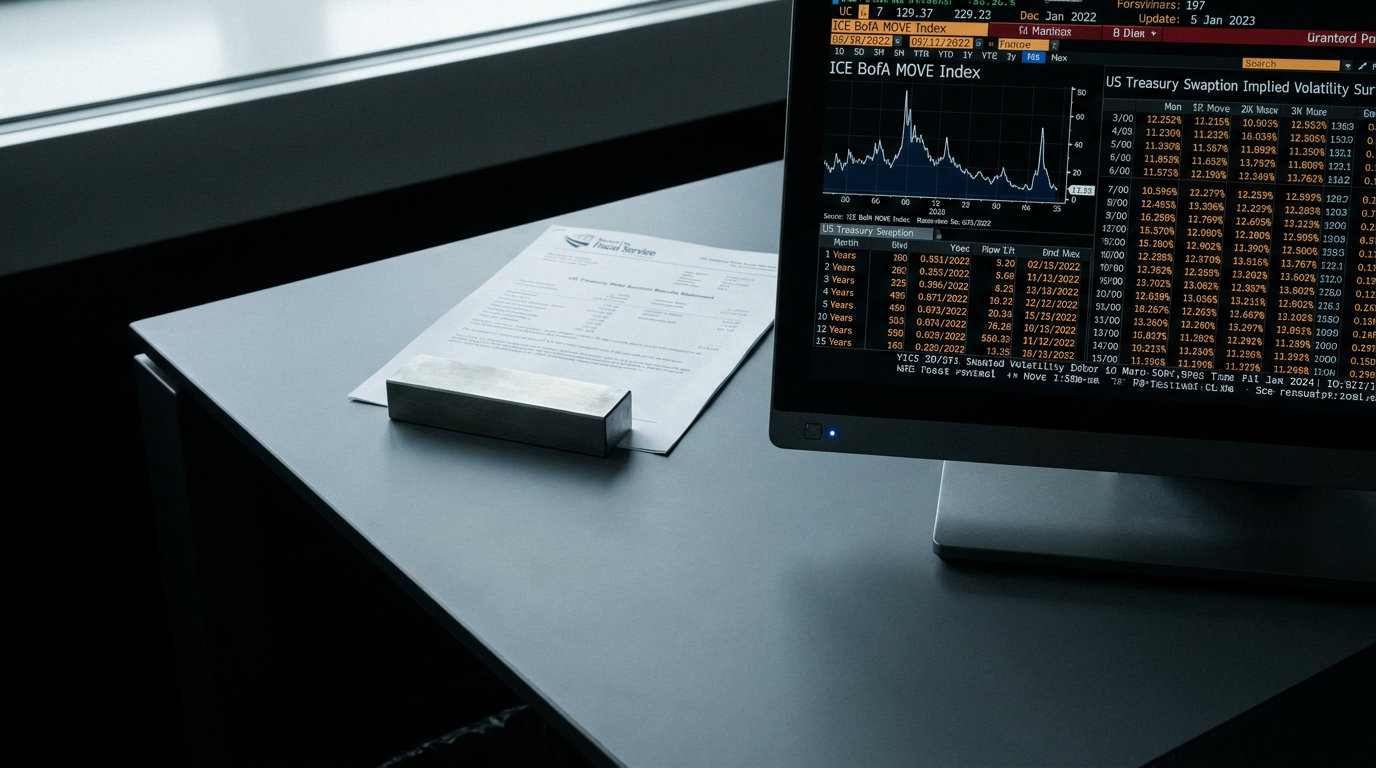
Fixed income markets have entered a protracted regime of elevated implied volatility, fundamentally altering the calculus for institutional balance sheets and sovereign debt managers. Over the past trading sessions, benchmark measures of rate uncertainty, most notably implied volatility extracted from intermediate and long-dated swaption matrices alongside the ICE BofA MOVE Index, have sustained levels well above their ten-year historical medians. Rather than representing an acute, transient reaction to specific data releases, this dispersion reflects structural recalibration across global duration markets.
Several concurrent developments account for this sustained turbulence. Primarily, central bank policy reaction functions have grown less deterministic. As inflation trajectories stabilize near target bands while fiscal deficits remain structurally expansive across developed markets, monetary authorities have retreated from explicit forward guidance. The absence of dogmatic policy signaling has reintroduced two-sided distribution risk into front-end and intermediate rate expectations. Consequently, institutional market participants can no longer underwrite policy easing cycles with the linear certainty that characterized previous monetary transitions.
Simultaneously, sovereign debt supply dynamics are compounding this instability. Unprecedented borrowing requirements from sovereign treasuries require constant capital absorption by private intermediaries and non-bank financial institutions. The cessation of balance sheet expansion by major central banks has stripped secondary sovereign debt markets of an insensitive, structural buyer of last resort. In its place, primary dealers and multi-strategy relative value funds must intermediate primary dealer auctions with constrained risk budgets, magnifying rate concessions during weekly refinancing cycles and widening term premiums across the yield curve.
For institutional allocators, the persistence of rate volatility imposes significant operational and portfolio construction challenges. Fixed income has historically functioned as an unencumbered ballast during periods of broader risk-off repricing. However, when sovereign paper exhibits localized annualized volatility exceeding that of traditional defensive assets, the correlation benefit of holding pure duration deteriorates. Risk parity frameworks and liability-driven investment vehicles have consequently been forced to adjust leverage parameters downward, suppressing outright risk capacity across multi-asset mandates.
Moreover, the cost of portfolio hedging has escalated noticeably. Payer swaptions and Treasury options now carry heavy premiums, discouraging institutional portfolios from executing dynamic tail-risk overlays. Instead, capital allocators are increasingly leaning into cash preservation, selective duration shortening, and collateral optimization strategies. Collateral velocity within sovereign repo facilities has tightened as market participants prioritize high-quality liquid collateral to buffer potential intraday margin calls precipitated by swift intra-yield shifts.
In the private markets and corporate credit arena, this heightened rate volatility regime acts as an implicit friction on corporate recapitalizations. While outright credit spreads have maintained relative composure, the underlying all-in yield variability makes medium-term capital budgeting precarious for corporate borrowers. Corporate treasurers are displaying marked hesitation in locking in long-tenor debt issuance, choosing instead to issue shorter-maturity paper or negotiate syndicated private credit solutions with bespoke covenant architectures, despite the incremental liquidity penalty.
From the vantage point of Zurich, Swiss and European wealth stewards observe that the structural end of quantitative easing continues to assert its second-order effects. The normalization of interest rate volatility is not merely an inconvenience for market makers, but a permanent structural realignment in asset pricing. Institutions managing perpetual capital must recognize that passive duration exposure requires substantial liquidity reserves and precise volatility attribution. Without an active understanding of interest rate variance risk, conventional fixed income allocations risk failing their traditional defensive mandate.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.