Sovereign Duration Dynamics
Long-End Duration Demand Defies Sovereign Issuance Pressures
2 November 2026
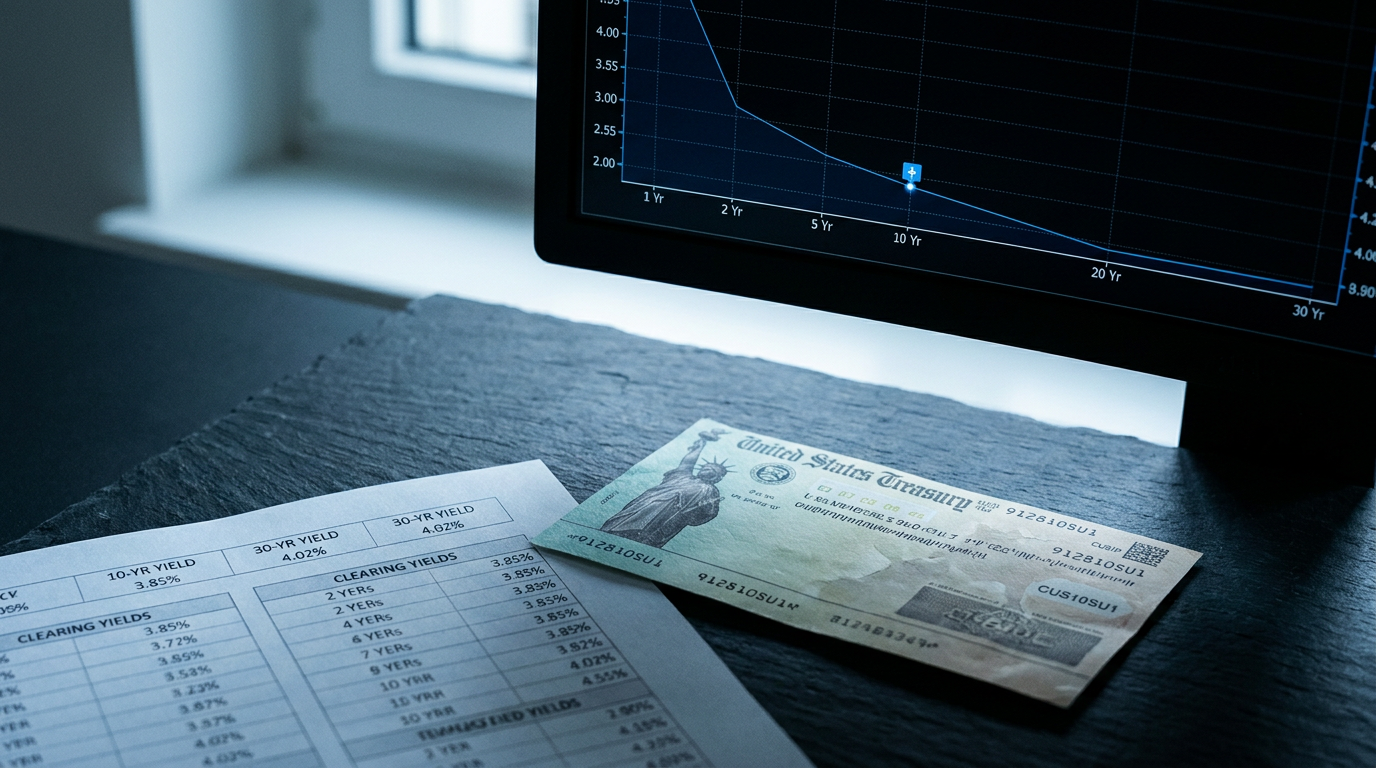
The persistent strength across long-dated sovereign debt markets continues to confound conventional macro underwriting models. Historically, expanding structural primary deficits, substantial refunding calendars, and election-cycle fiscal uncertainty would dictate a discernible expansion in term premiums. Under traditional pricing frameworks, primary dealers and non-bank institutional market participants demand yield concessions to absorb escalating duration risk. Yet benchmark ten-year and thirty-year sovereign curves have exhibited robust bid-side depth, flattening long-end forward curves even as baseline supply metrics expand.
A primary catalyst for this counter-intuitive duration absorption lies in the structural mechanics of liability-driven balance sheet repositioning. Defined-benefit pension sponsors and continental European life insurers, operating under stringent regulatory solvency regimes, have utilized the late-cycle rate plateau to execute systematic liability immunization. With high-grade corporate credit spreads trading near multi-year tights, the incremental spread pickup offered by corporate debt provides inadequate risk compensation relative to its credit and liquidity profiles. Consequently, institutional portfolio managers have pivoted decisively toward high-grade sovereign paper, prioritizing high-quality nominal yield locks over spread risk.
This behavior has created a marked divergence between front-end monetary policy pricing and long-end curve clearing dynamics. While front-end money market instruments remain tethered to sticky policy rates and central bank caution regarding underlying services inflation, the long end is increasingly pricing structural terminal growth constraints. Fixed-income capital is effectively underwriting a macro regime where elevated public debt servicing costs crowd out future fiscal flexibility, placing a long-term ceiling on trend productivity and real neutral rates. While quantitative tightening and dealer inventory pressures were forecasted to disrupt market depth, non-bank asset managers have routinely stepped into auction tails, mopping up duration supply without necessitating deep concessionary discounts.
Cross-border capital allocations have reinforced this compression. Non-domestic reserve allocators and European real-money accounts, navigating asymmetric foreign exchange hedging costs and tighter domestic swap spreads, have deployed excess liquidity into long-dated US and core sovereign issues. Securing unhedged or selectively hedged real yields above historical decile averages has proven attractive for foreign asset managers anticipating eventual cyclical deceleration across developed economies. This cross-currency duration bid has acted as a synthetic ceiling on long-term yields, offsetting the upward pricing pressure that normally accompanies heavy government debt issuance.
Market plumbing dynamics further illuminate this stability. Heavy usage of sovereign paper within collateralized financing arrangements and bilateral repo facilities has sustained a baseline level of structural demand that operates independently of cyclical rate expectations. High-quality liquid assets remain in sustained demand across global clearing systems, ensuring that primary auction allocations are rapidly redistributed into custody accounts rather than lingering as unhedged inventory on primary dealer balance sheets.
For institutional allocators, the durability of this duration rally poses critical structural questions. If treasury issuance continues to skew toward the long end without triggering commensurate term premium expansion, secondary market liquidity risks becoming increasingly bifurcated between high-velocity on-the-run issues and illiquid off-the-run inventory. The current pricing environment demonstrates that sovereign duration is currently being governed by institutional balance-sheet mandates and regulatory liability requirements, rather than conventional cyclical growth expectations alone.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.