Sovereign Entitlement Indexation
Sovereign Entitlement Indexation Reshapes Inflation Hedging
31 October 2026
The intensifying fiscal debate in Washington regarding statutory cost-of-living adjustments for entitlement obligations marks a pivotal juncture for sovereign liability management. Long regarded as an immutable component of post-war social contract design, the indexation formula governing programmatic disbursements is facing structural scrutiny under the weight of compounding debt service costs and unfunded demographic liabilities. As federal debt trajectories intersect with terminal funding horizons for major entitlement trust funds, policy proposals to transition from traditional price metrics toward chained inflation indices or capped adjustment mechanisms have ceased to be peripheral academic exercises. For institutional capital allocators, this shift signals far more than legislative bargaining; it reflects the inevitable friction between sovereign solvency mandates and statutory real-return guarantees.
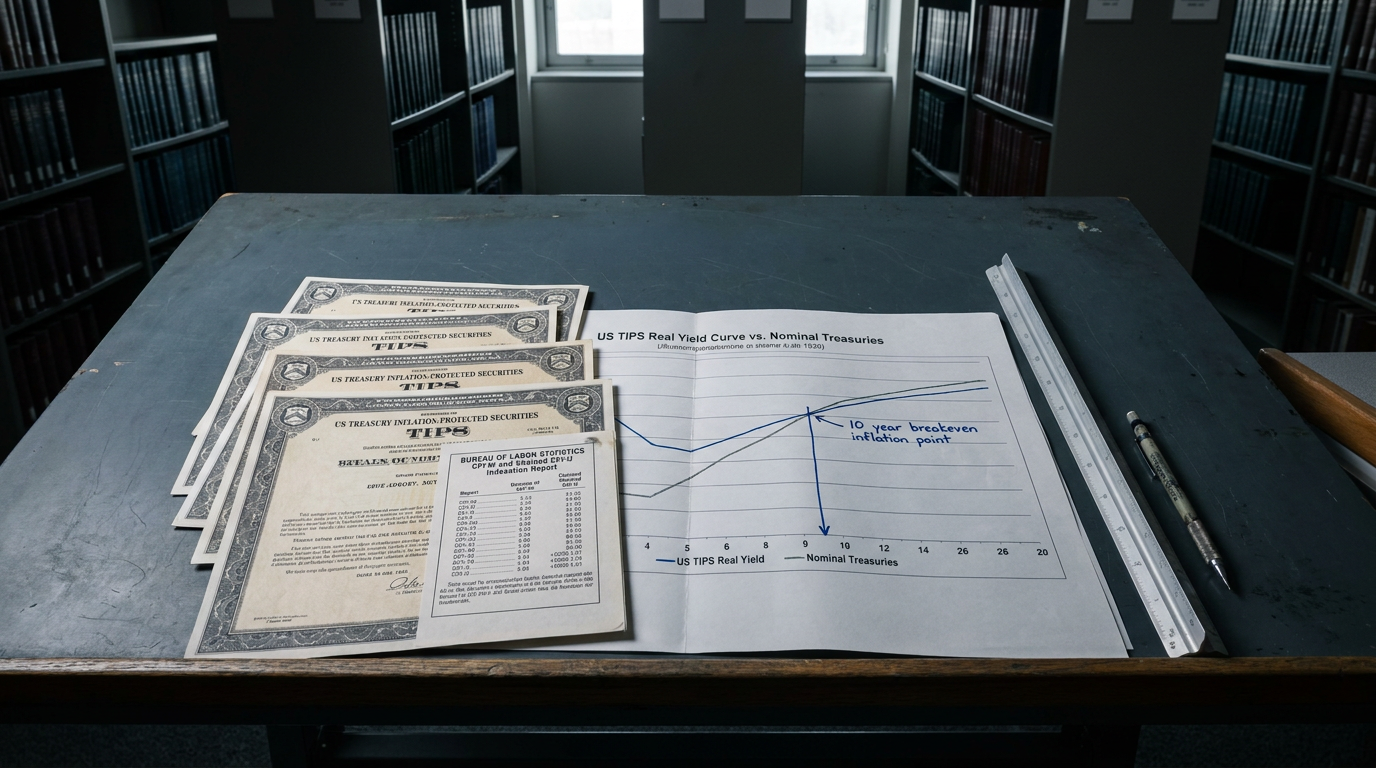
The direct financial transmission channel operates through the sovereign debt architecture, specifically the valuation of inflation-hedging instruments and long-dated real yields. Markets have long treated consumer price indices as an objective baseline for cost inflation, embedding these assumptions across Treasury Inflation-Protected Securities and related swap structures. When policy discussions contemplate altering statutory indexation—such as migrating from the headline Consumer Price Index for Urban Wage Earners and Clerical Workers toward the Chained Consumer Price Index for All Urban Consumers—they directly impact expected forward sovereign cash outflows. At scale, an incremental reduction of fifty to seventy-five basis points in annual programmatic indexation alters the cumulative borrowing requirements of the sovereign across multi-decade horizons by trillions of dollars. This prospective deceleration in net issuance requirements at the long end of the curve exerts downward structural pressure on long-tenor term premia.
Simultaneously, the private liability-driven investment sector is forced to recalibrate its asset-liability matching assumptions. Defined-benefit pension sponsors and institutional life insurers construct long-duration asset portfolios predicated on prevailing statutory inflation definitions and demographic decumulation pathways. If sovereign safety nets compress statutory real purchasing power replacement rates, private households inevitably alter their aggregate savings and withdrawal patterns. The phenomenon of precautionary capital retention among aging cohorts—manifesting as an aversion to systematic decumulation even in well-funded tranches—intensifies demand for private capital preservation vehicles. Institutional sponsors must consequently navigate an environment where participant annuitization behavior diverges sharply from historical actuarial models, increasing liquidity buffers and compressing duration appetite across corporate credit.
The ramifications also extend into the relative pricing of inflation compensation across public markets. While statutory entitlement indexation changes do not mechanically alter the contractually settled coupon calculations of existing Treasury Inflation-Protected Securities, they fundamentally alter the broader macro aggregate demand profile. A structural deceleration in programmatic transfer payments curbs real household consumption among lower- and middle-income demographics, muting underlying demand-pull inflationary impulses over intermediate cycles. In response, long-dated breakeven inflation rates across the five-to-ten-year curve have begun to reflect a more subdued terminal inflation premium, reflecting market recognition that sovereign entitlement reform represents a form of structural fiscal tightening by attrition.
Furthermore, the debate highlights the shifting boundary between sovereign balance sheets and private household balance sheets. Over the past five decades, sovereign indexation mechanisms absorbed the bulk of macro tail risks associated with persistent monetary depreciation. As policymakers contemplate shifting an increased quantum of real longevity and purchasing power risk onto individual balance sheets, private wealth intermediation structures face renewed capital allocation demands. Fixed-income laddering strategies, structured capital-preservation notes, and high-quality liquid assets are capturing institutional flows previously targeted at discretionary credit exposures. This subtle migration toward capital preservation dampens risk velocity across downstream private equity and subordinated real estate tranches.
Ultimately, the institutional reassessment of cost-of-living mechanics reflects an acknowledgment that sovereign fiscal space is entering an era of explicit constraints. For macro allocators and multi-asset fiduciaries, the erosion of statutory inflation indexation underscores the imperative of decoupling liability benchmarks from political assurances. As the legislative trajectory unfolds, market pricing across the sovereign curve will increasingly differentiate between nominal issuance volume, sovereign solvency adjustments, and the structural transfer of real inflation risk to private capital markets.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.