Quick-Service Capital Intensity
Quick-Service Overhauls Expose Private Equity Underwriting
28 October 2026
The emergence of sponsor interest and acquisition proposals surrounding mature quick-service restaurant franchisors, highlighted most recently by buyout overtures targeting The Wendy’s Company, brings into sharp focus an underlying friction within consumer-facing private capital underwriting. For over a decade, public equity markets rewarded asset-light franchisors with elevated valuation multiples, prizing predictable royalty revenues that insulated parent companies from real estate ownership and store-level operating volatility. However, the physical reality of aging fast-food store footprints is now colliding with tighter credit markets and declining consumer elasticity, revealing that modernising legacy operations will prove far more capital-intensive than prior buyout cycles suggested.
The strain begins at the unit level. Cumulative cost inflation across store-level labor, utility tariffs, and wholesale agricultural inputs has steadily eroded franchisee profitability over the past four years. While initial menu price increases temporarily preserved restaurant-level operating margins, elasticity thresholds have been reached. Foot traffic among middle- and lower-income demographic cohorts has contracted noticeably, constraining top-line volume growth. As a result, independent franchisee operators—who are typically responsible for funding store remodels, digital integration, and kitchen equipment upgrades out of operational cash flow—face compressed debt-service coverage ratios and diminishing free cash balances.
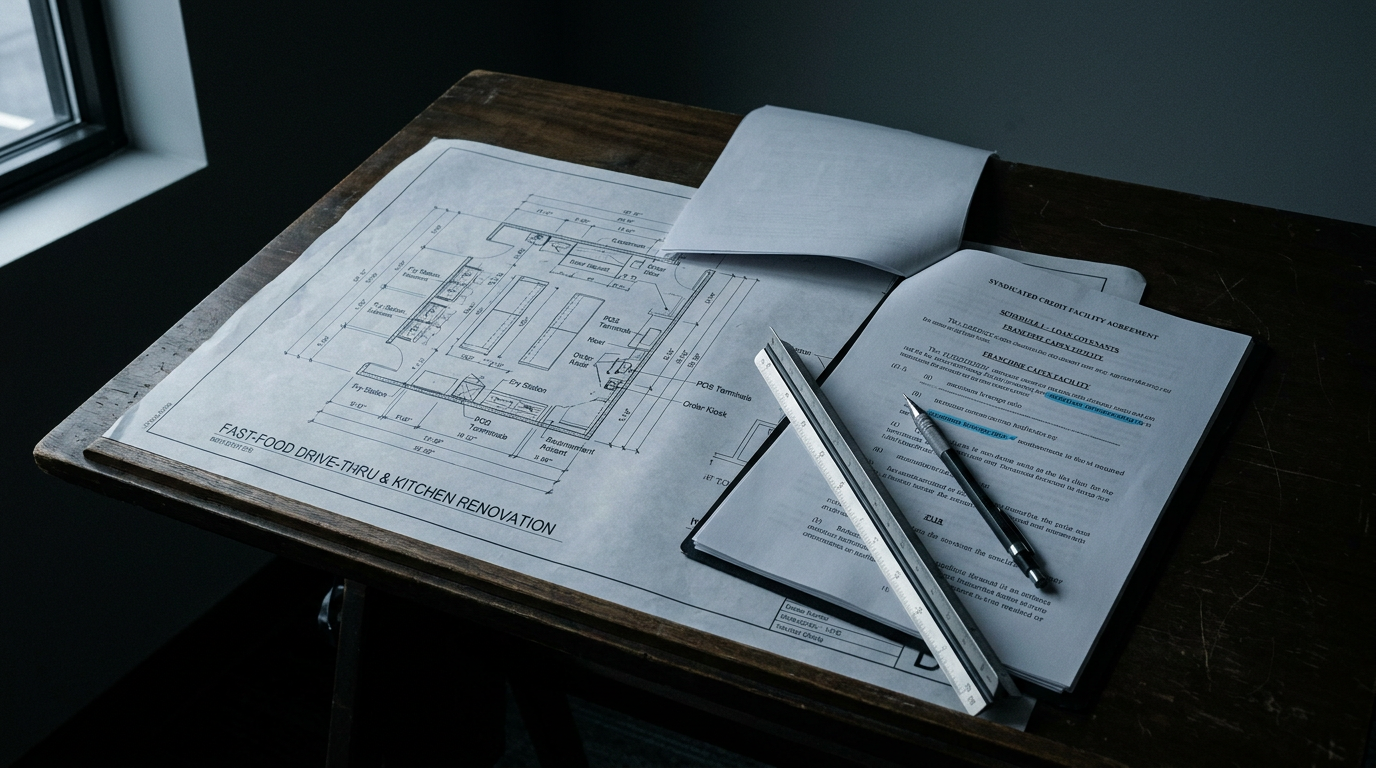
In this environment, corporate franchisors can no longer rely on franchisees to unilaterally absorb the costs of brand modernization. Keeping pace with digital ordering standards requires more than superficial aesthetic updates; it entails deploying dual-lane automated drive-thru systems, bespoke mobile order staging spaces, dedicated curbside pickup infrastructure, and high-efficiency kitchen platforms engineered to reduce unit labor demand. The capital expenditure for a comprehensive store retrofit has escalated substantially, often exceeding several hundred thousand dollars per location. With regional bank lending for commercial franchise equipment remaining tight and expensive, parent companies or prospective private equity acquirers are forced to step in with corporate co-investment facilities, remodeling allowances, or direct capital grants.
This necessity fundamentally alters the mechanics of leveraged buyouts in the quick-service space. Historically, private equity sponsors relied on the whole-business securitization market or high-yield syndicated debt to extract large dividend recapitalizations against franchise royalty streams, allocating minimal corporate capital to physical assets. Today, the syndicated debt market demands wider spreads, and credit rating agencies are rigorously stress-testing franchisee viability and system-wide debt sustainability. Buyout models must now factor in hundreds of millions of dollars in near-term parent-level capital expenditure just to stabilize market share, eroding the free cash flow yield available to service acquisition leverage.
The friction is further accentuated by divergent priorities between public equity holders and prospective private acquirers. Public investors have persistently demanded continuous capital returns in the form of regular dividends and opportunistic share buybacks, which routinely stripped franchisor balance sheets of liquidity that might otherwise have bolstered franchise co-investment funds. When a financial sponsor steps forward to privatize such an entity, the transaction thesis cannot merely rely on taking public cash flows private; it demands an aggressive operational turnaround plan wherein distributions are subordinated to physical renovation. This creates an immediate valuation gap during takeover negotiations, as target boards anchor their expectations to historic cash-generation metrics while acquirers discount bids against mandatory forward capital commitments.
For institutional asset managers and credit underwriting teams, the restructuring unfolding across the quick-service segment serves as a microcosm of broader corporate capital expenditure realities. The frictionless asset-light model that proliferated during years of zero-interest-rate policy is reaching its structural limits. When the maintenance and technological enhancement of physical commercial assets are deferred for too long, the deferred bill eventually accrues back to the parent balance sheet. Sponsors evaluating consumer retail platforms must balance the allure of contracted royalty income against the capital demands of an aging estate, where preserving brand competitiveness requires hard balance sheet deployment rather than mere financial leverage.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.