Corporate Guidance Deflation
Corporate Guidance Deflation Tests Large-Cap Equity Valuations
25 October 2026
Global equity markets closed the final full trading week of October under pronounced institutional de-risking, as participants prepared for an unprecedented concentration of corporate disclosures. With more than a third of S&P 500 constituents scheduled to report third-quarter operating results over the coming days, the market's fragile consensus around margin durability encountered acute friction. Selling pressure on Friday reflected a broader reassessment of corporate profitability against prevailing interest rates, compounding seasonal risk aversion ahead of the approaching United States midterm elections.
While historical precedent frequently points to fourth-quarter seasonal relief once electoral outcomes are settled, institutional market participants are increasingly differentiating between cyclical political overhangs and structural microeconomic headwinds. The current compression in valuation multiples does not merely stem from policy uncertainty; it reflects an unambiguous deceleration in forward corporate guidance. Across consumer discretionary, manufacturing, and legacy software segments, management teams have exhibited marked reluctance to underwrite aggressive 2027 consensus estimates, opting instead to guide expectations lower in an effort to insulate share prices against subsequent execution shortfalls.
The negative-to-positive pre-announcement ratio has deteriorated noticeably over the past two weeks. Companies that benefited from pricing power throughout the preceding inflationary cycle are finding that unit volume degradation now offsets margin realization. Concurrently, labor expense rigidity and elevated debt refinancing charges are beginning to exert tangible pressure on interest coverage ratios. For non-hyperscale corporate balance sheets, discretionary capital expenditure is being subjected to stringent internal hurdle rates, manifesting in deferred enterprise software deployments and curtailed facility upgrades.
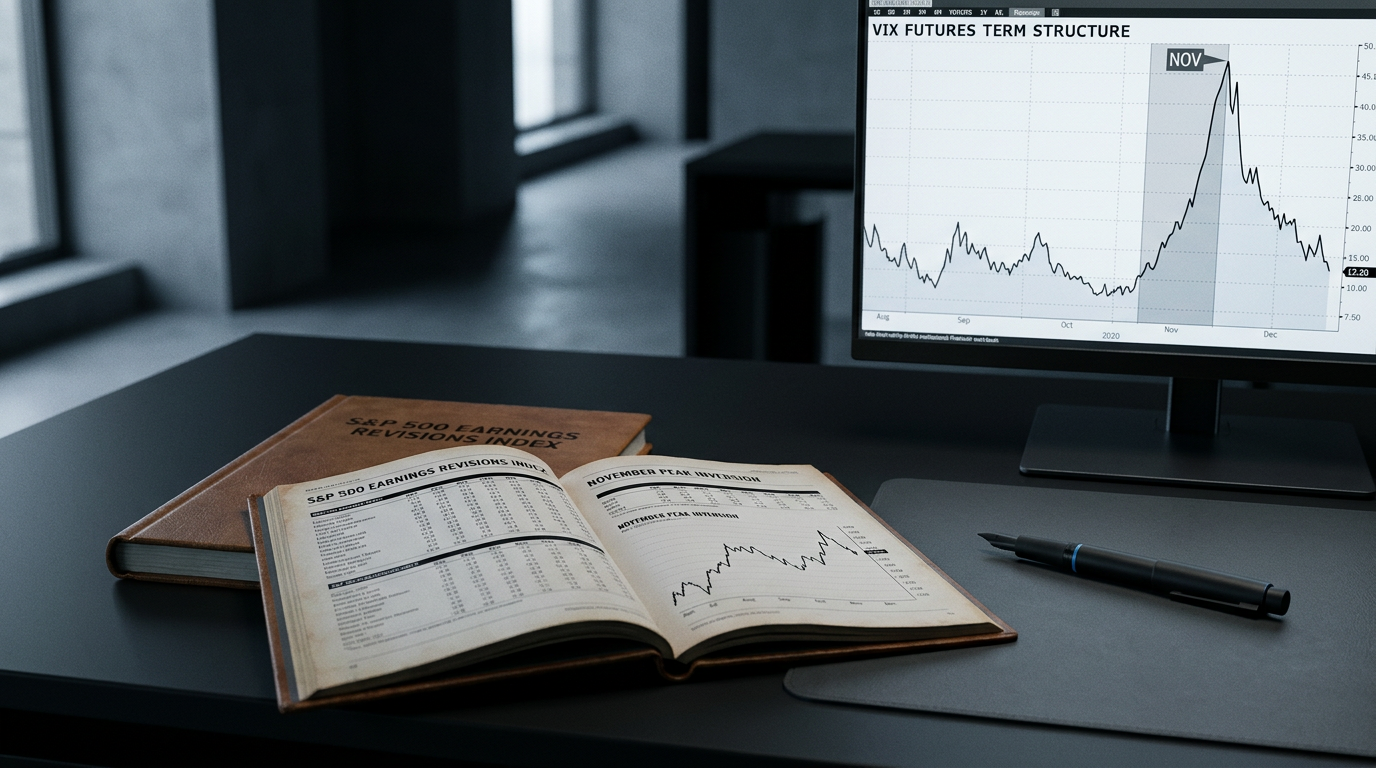
This fundamental shift has exerted significant mechanical pressure across equity derivative markets. The implied volatility surface on benchmark index options displays an acute kink centered on early November, illustrating elevated demand for asymmetric downside protection. Rather than liquidating physical equity holdings, institutional allocators have largely leaned into synthetic hedging, utilizing index collar overlays and calendar put spreads. This hedging activity has widened the implied-to-realized volatility spread, indicating that while institutional balance sheets remain invested, their tolerance for single-stock earnings surprises has reached a cyclical low.
From our vantage point in Zurich, the confluence of heavy earnings concentration and electoral hedging highlights the limitations of mechanical seasonal positioning. Market narratives that anticipate an automatic post-election relief rally presuppose an underlying earnings trajectory that current corporate disclosures fail to corroborate. When guidance revisions turn systematically negative in a high-cost-of-capital environment, valuation multiples must adjust to reflect lower terminal cash flows rather than temporary sentiment. A prudent allocative stance therefore prioritizes capital preservation and balance-sheet solvency over speculative timing around broad index recovery.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.