Equity Breadth Dispersion
Equity Breadth Dispersion Deepens Amid Rising Hurdle Rates
18 October 2026
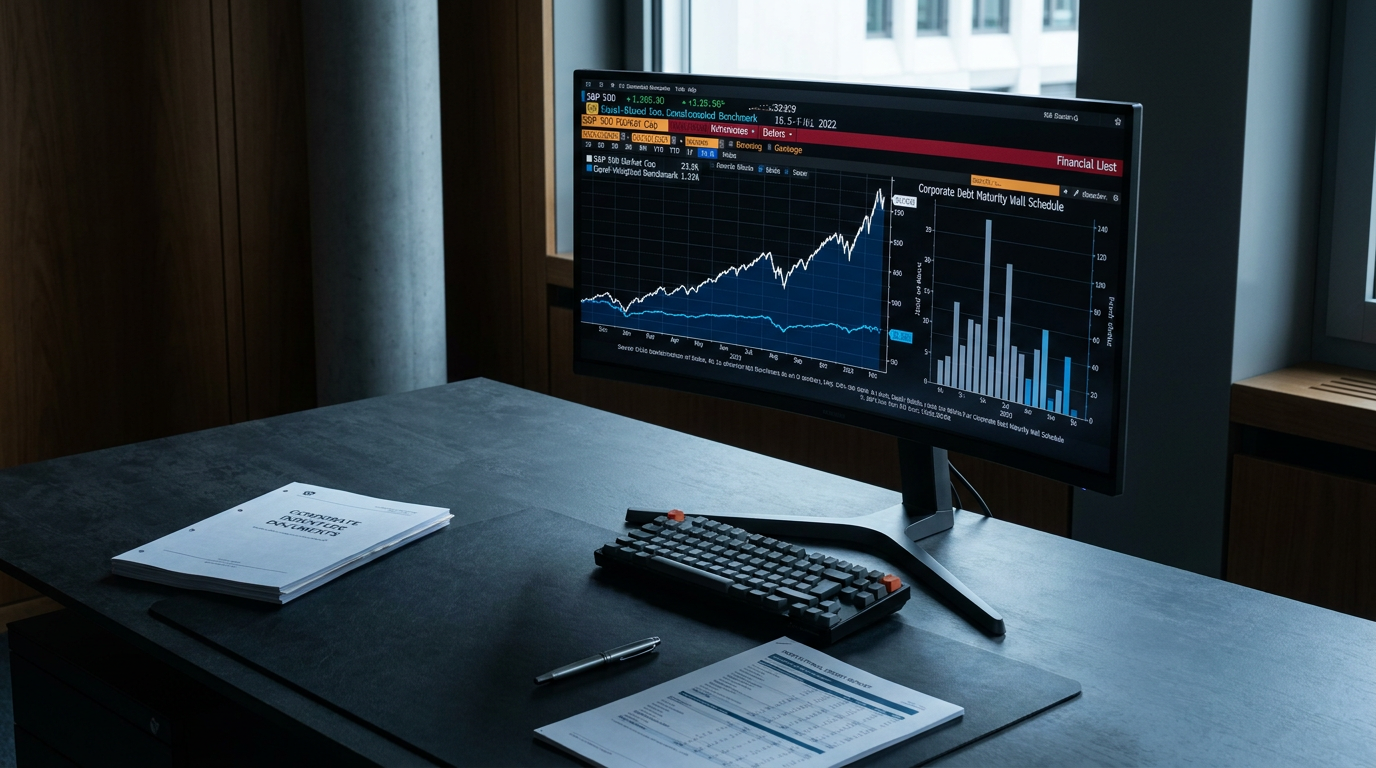
Broad equity benchmarks concluded the trading week near cyclical highs, yet internal participation metrics reveal acute divergence across individual constituents. While aggregate capitalization-weighted earnings metrics continue to be buttressed by secular pricing power and fortress balance sheets among the largest index members, the median firm confronts an increasingly restrictive capital regime. The widening spread between headline index stability and deteriorating underlying market breadth highlights an escalating collision between operational margins and embedded debt service across secondary and tertiary tiers of corporate equity.
This structural bifurcation reflects the progressive expiration of medium-term corporate debt facilities underwritten during the accommodative monetary regime of 2020 and 2021. For the largest multi-hundred-billion-dollar capitalization tier, elevated base rates have exerted negligible drag; substantial liquid reserves parked in front-end sovereign instruments have effectively neutralized gross interest expense through accretive net cash balances. In sharp contrast, capital-intensive industrial operators, consumer discretionary manufacturers, and mid-tier constituent enterprises are encountering roll-over coupons between 300 and 450 basis points higher than expiring paper. This refinancing friction is steadily truncating free cash flow conversion across the bottom four quintiles of benchmark market weight.
Institutional transaction flows throughout Friday underscored this quiet reallocation across global asset managers. Rather than precipitating broad, indiscriminate de-risking, trading desks noted systematic factor rotation prioritizing unlevered return on invested capital over top-line revenue expansion. The equal-weighted S&P 500 lagged its market-cap-weighted counterpart materially, extending a divergence that historically presages late-cycle earnings recalibrations. When benchmark progression relies disproportionately on an ultra-narrow cluster of balance sheet fortresses, overall index vulnerability to idiosyncratic earnings disappointments increases exponentially.
Compounding this dispersion is the delayed transmission mechanism within consensus equity research. Sell-side consensus forward estimates have been remarkably slow to incorporate the compounding burden of higher debt service on post-interest net income. While operating income margins have appeared superficially resilient due to past price increases, interest expense line items are beginning to swell rapidly as rolling revolving facilities and floating-rate working capital revolvers reprice. As third-quarter reporting season broadens, forward guidance is beginning to decouple sharply between issuers with entirely self-funding balance sheets and those constrained by ongoing secondary market underwriting dependencies.
Furthermore, the friction extends directly into corporate capital deployment strategies. Constituents with elevated leverage ratios are increasingly forced to curtail discretionary capital expenditure and share repurchase authorizations in order to defend investment-grade credit metrics. This defensive retrenchment, while prudently preserving debt coverage ratios, directly impairs multi-year organic growth trajectories. Equity markets are punishing this capital rationing, producing severe intra-sector valuation dispersion even within industries that exhibit seemingly uniform top-line end-market demand.
The credit secondary market reinforces this bifurcation. Although high-grade aggregate credit spreads remain compressed near multi-year tights, the appearance of systemic liquidity is deceptive. Tighter spreads are predominantly concentrated in the most liquid benchmark paper of prime balance sheets. By contrast, secondary market bid-ask spreads for BBB-rated crossover tranches and subordinated paper have widened, reflecting institutional reluctance to absorb refinancing risk without punitive concession pricing. Equity factor models are increasingly synchronizing with these subtle credit tiering signals.
From an institutional perspective at Fairclough Palmer, our analysis indicates that headline index momentum provides a misleading signal of systemic corporate health. The divergence between index-level valuation stability and median constituent liquidity stress represents a fundamental repricing of capital durability in a higher-for-longer hurdle rate environment. Portfolio construction must look past composite index multiples to examine debt maturity ladders, covenant headroom, and genuine net cash generation, distinguishing enterprises that control their financing destiny from those whose operational viability remains tied to debt roll-over friction.
This commentary is provided for general information only and does not constitute investment, legal or tax advice.